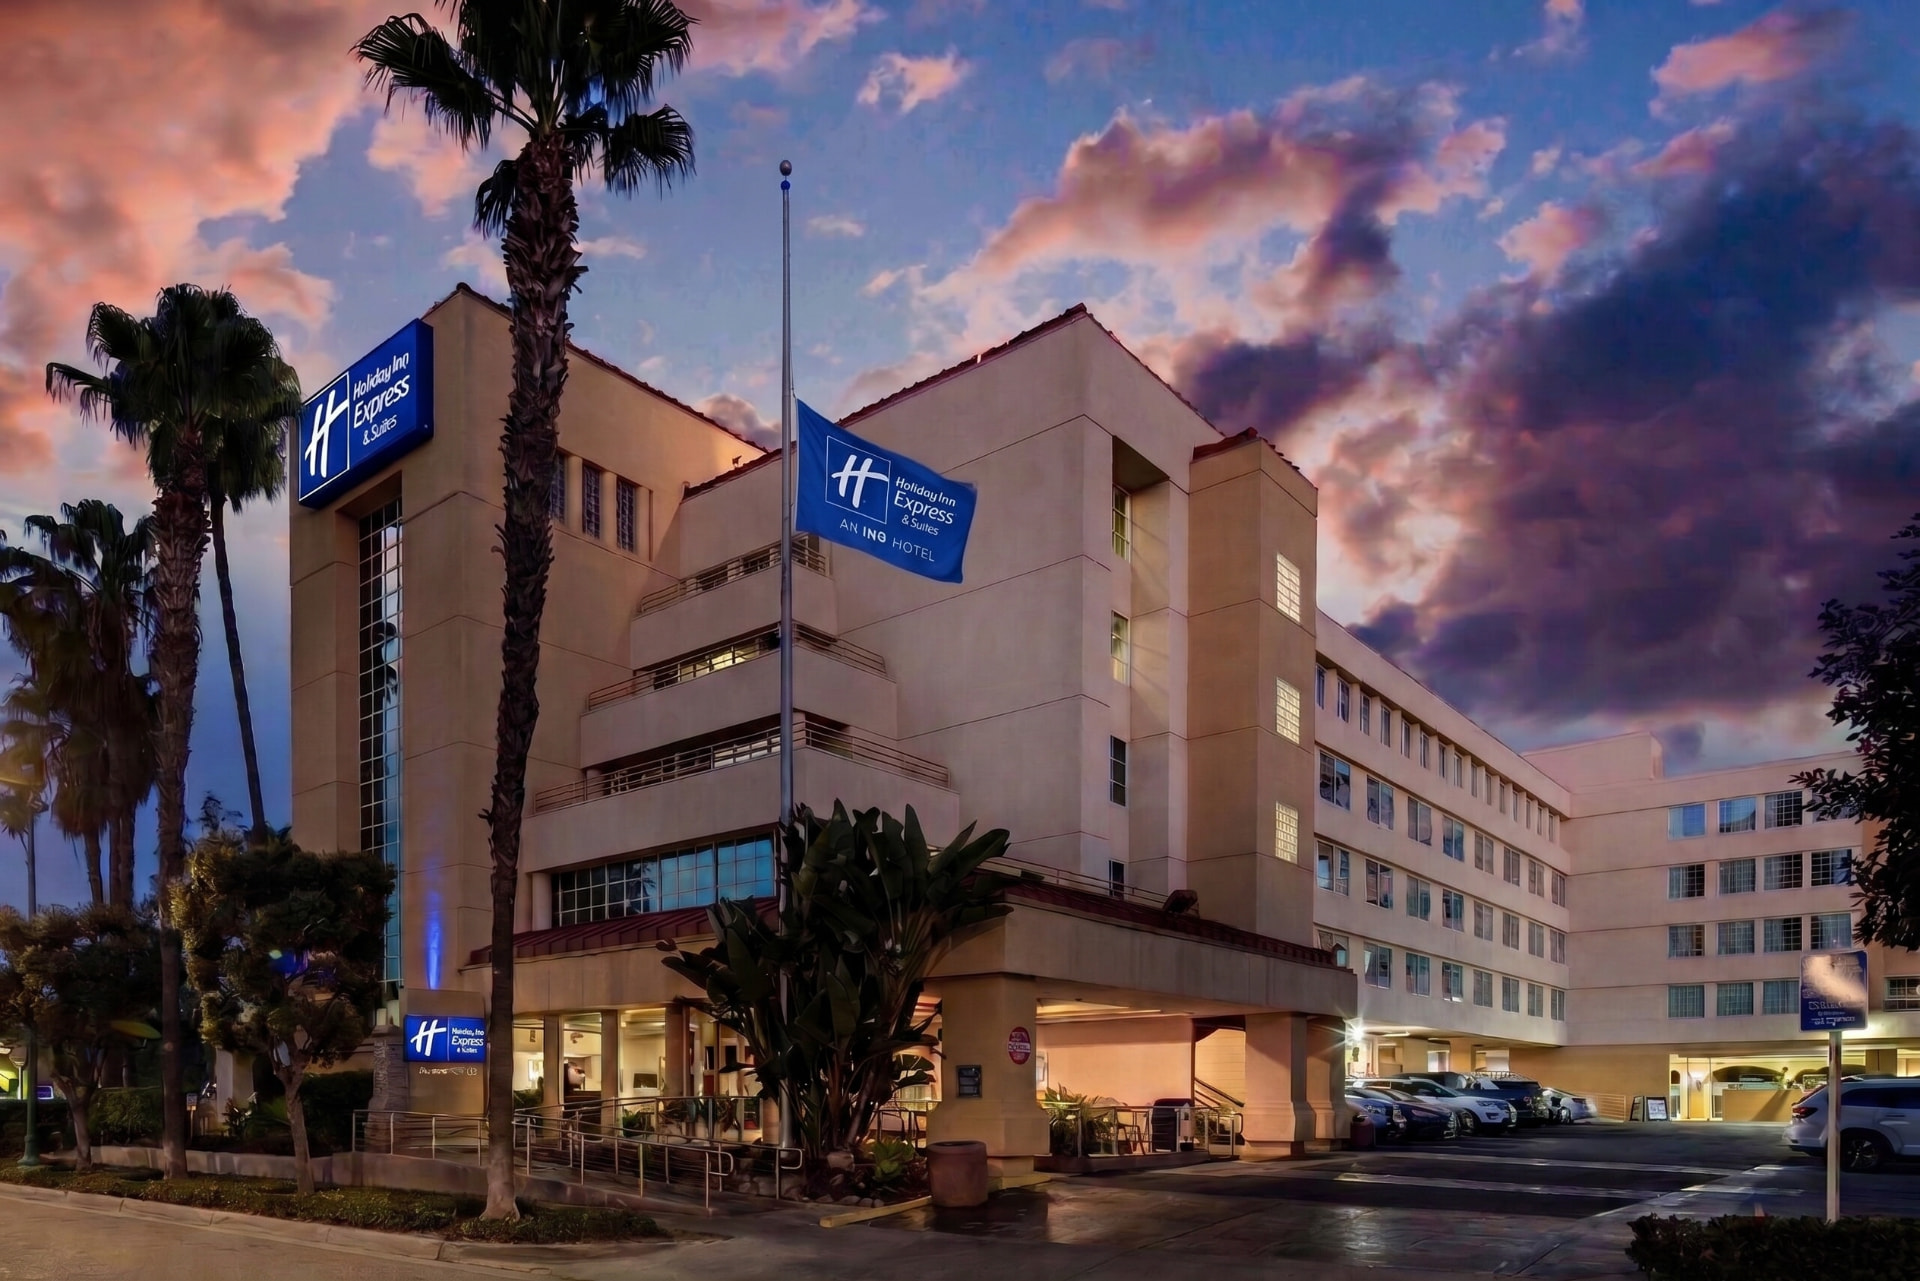
Front exterior of the 129-key Anaheim hotel with Holiday Inn Express & Suites signage at dusk

Verifiable Accredited Investors Only · Reg D Rule 506(c)

Reflagging of Disneyland Anaheim Resort Hotel

Converting a dated La Quinta Inn & Suites to a Holiday Inn Express & Suites, operated by NewcrestImage Management LLC, one half mile from the Disneyland Resort gates and 0.4 miles from the Anaheim Convention Center.

$250M+ Raised36 Full-Cycle Closed Investments by Moneil Investment Group

Section 01 · Sponsor Briefing

Hear the opportunity from the sponsor.

We walk through the asset purchase, the conversion, and how the sponsorship underwrites it.

Section 02 · The Thesis

A below replacement cost asset, at 40% of replacement cost, with a stronger flag and a market that does not build.

01

Location is the driver

Walking distance to the Disneyland Resort gates and the Anaheim Convention Center, in a district that recorded 26.5M visitors and $6.8B of visitor spending in 2025. A $1.9B+ minimum expansion program funds roadway work on Clementine Street itself.

02

A stronger flag, below replacement cost

A tired La Quinta acquired at $162,791 per key and $233,941 all-in, re-flagged to Holiday Inn Express & Suites with $1.548M of IHG key money ($12,000/key) paid pari passu to investors. IHG holds just 611 of roughly 21,000 rooms in the market.

03

Experienced operator and sponsorship

Moneil Investment Group leads the sponsorship and its principals are co-borrowers on the loan. Day-to-day operations run through NewcrestImage Management LLC, with 300+ hotel deals and $3B+ transacted.

$21.0MPurchase price
$162,791Price / key
$30.178MTotal capitalization
$12.07MTotal equity

Section 03 · The Asset

129 keys on a long-dated leasehold at 1752 S. Clementine Street.

A five-story, 129-key hotel built in 1992, held on a triple-net ground lease with roughly 70 years remaining, acquired at a basis below replacement cost in the Anaheim Resort District.

Front exterior of the 129-key Anaheim hotel with Holiday Inn Express & Suites signage at dusk
Arrival & exterior — post-conversion design intent
129Guestrooms
5Stories
70 yrLease remaining

Property Specifications

Address
1752 S. Clementine St, Anaheim, CA 92802
Guestrooms
129 · 55 two-double · 30 king · 44 suites
Current flag
La Quinta Inn & Suites (Wyndham)
Target flag
Holiday Inn Express & Suites (IHG)
Year built
1992 · 5 stories
Operator
NewcrestImage Management LLC
Market / submarket
Anaheim, CA · Anaheim Resort / Platinum Triangle
Land tenure
Leasehold to 2096 · ~70 years remaining · triple-net
Ground rent
$541K/yr · CPI resets every 4 years (10–25% collar)
Purchase price
$21.0M leasehold · $162,791 / key
Total capitalization
$30.178M · $233,941 / key
Senior debt
$18.1M · 60% LTC · 8.0% fixed · 2-yr interest-only

Section 04 · Thesis Returns

Thesis returns, net to the limited partner.

Underwritten to a Year-3 institutional sale at an 8.2% exit cap, after fees and promote.

21.8% – 23.2%

Thesis net LP IRR

Class A / Class B, Year-3 exit

1.74x – 1.80x

Thesis equity multiple

Net to the limited partner

3 – 4 Yrs

Projected hold period (Thesis)

Thesis Year-3 disposition

Limited Partner A

$250K – $499K

Minimum
$250,000
Operating split
70/30 LP/GP
Thesis net IRR
21.8%
Thesis multiple
1.74x

2% annual asset-management fee · 2% loan guaranty fee

Limited Partner B

$500K and above

Minimum
$500,000
Operating split
75/25 LP/GP
Thesis net IRR
23.2%
Thesis multiple
1.80x

2% annual asset-management fee · 2% loan guaranty fee

Targets are projections based on sponsor underwriting assumptions. They are not guarantees. Actual results may differ materially, and investors may lose some or all of their capital.

Request the Full Financial Package

Released to verified accredited investors only

Section 05 · Tax Advantages

A $5.4M renovation creates the depreciable basis. Bonus depreciation does the rest.

88%Thesis 3-year profit · Class A investors
94%Thesis 3-year profit · Class B · $500K+
50–60%Est. K-1 loss · Year 1 · 2026
50–60%Est. K-1 loss · Year 2 · 2027
~110–120%Cumulative 2-year tax loss vs. capital

The $5.418M property improvement plan creates a large depreciable basis at closing. A cost segregation study reclassifies components of that spend into 5-, 7-, and 15-year assets, which accelerates how quickly they can be written off.

100% bonus depreciation is permanent under the OBBBA for property placed in service after January 19, 2025, so a large share of those reclassified components can be deducted in the first year rather than over decades.

Those paper losses pass through to limited partners on a K-1. A passive investor may be able to use them to offset qualifying passive income. Passive losses generally offset only passive income unless the investor qualifies for Real Estate Professional Status.

This is general information, not tax advice. Actual allocations depend on the final cost segregation study, the placed-in-service date, and your individual tax position. Consult your own CPA before investing.

How the benefit works

  1. 01

    Large PIP

    $5.418M ($42,000/key) renovation creates a large depreciable basis at closing.

  2. 02

    Cost segregation study

    Reclassifies components into 5-, 7-, and 15-year assets for accelerated depreciation.

  3. 03

    100% bonus depreciation

    Permanent first-year write-off under the OBBBA for property placed in service after January 19, 2025.

  4. 04

    K-1 pass-through

    Paper losses pass to limited partners via K-1, available to offset qualifying passive income.

Illustrative K-1 tax losses

Illustrative K-1 tax losses by investment amount
Tax yearEst. loss (% of capital)On $250KOn $500K
2026 (Yr 1)50–60%$125K–$150K$250K–$300K
2027 (Yr 2)50–60%$125K–$150K$250K–$300K
2-Yr cumulative~110–120%~$275K–$300K~$550K–$600K

Illustrative estimates only. Actual allocations depend on the final cost-segregation study, placed-in-service date, current tax law, and each investor’s individual tax position. Passive losses generally offset passive income unless the investor qualifies for Real Estate Professional Status. Consult your own tax, legal, and financial advisors.

Section 06 · Track Record

Real hotels. Real returns. Real investors paid.

Moneil Investment Group's hospitality journey spans seven hotel purchases and developments — from a completed ~400% IRR exit to active Hilton, Marriott, and IHG projects. Past performance is not a guarantee of future results.

Current 506(c) Offering

Holiday Inn Express Anaheim Resort

1752 S. Clementine St · Anaheim, CA · 129 Keys · 5 Stories

21.8–23.2%Thesis IRR
1.74x–1.80xEquity multiple
40%Of replacement cost
$30.178MTotal project cost

IHG-approved conversion of a 129-key La Quinta less than a mile from Disneyland and 0.4 miles from the Anaheim Convention Center. $5.418M PIP fully scoped; $1.548M in IHG key money paid pari passu to investors. LP-A ($250K+): 70/30 split. LP-B ($500K+): 75/25 split.

Fully Subscribed · Renovating

Marriott Downtown Columbus

50 S. Front Street · Columbus, OH · 194 → 230 Keys · 16 Floors

21.21–22.60%Thesis IRR
1.71x–1.76xEquity multiple
$13MBank-owned purchase
$100MReplacement cost

Full-service Marriott flagship conversion in Downtown Columbus. The 194-suite property is being expanded to 230 keys through a $25M+ transformation, including 10,000+ SF of meeting space, an M Club, lobby bar, and outdoor pickleball courts.

Successfully Exited · ~400% IRR

Hilton Garden Inn McAllen

McAllen, TX · 104 Keys · Acquired from Blackstone · Dec 2019

$6.3M → $12MPurchase → sale
~400%IRR delivered
2.5 YearsHold period
80%+Occupancy (COVID)

Acquired off-market from Blackstone weeks before COVID-19. The team captured hospital and nursing staff demand, achieving 80%+ occupancy throughout the pandemic. Nearly doubled asset value in 2.5 years. Used $5.3M of sale proceeds in a 1031 Exchange into Casa de Palmas.

Operating · Appreciating

Casa de Palmas

Downtown McAllen, TX · 165 Keys (incl. 24 Suites) · Wyndham Trademark · Built 1918

$13.7M → $17MPurchase → value
95%Occupancy rate
4.2 / 5Google rating (1,121 reviews)
$3.3MValue appreciation

Historic Texas landmark acquired as lender-owned REO (1031 exchange from Hilton Garden Inn). Transitioned from receiver management to owner-operator. Features 11 event venues, 6,621 SF event space, The Spanish Room restaurant, and Cantina Lomax lounge.

Active · Renovating

Courtyard Marriott Legacy West

Plano, TX · 153 Keys · Bank-Owned Acquisition · 35 Competing Offers

$14.5MBank-owned acquisition
$6MBelow replacement cost
$3.97MGen 6 PIP renovation
$20.46MTotal all-in basis

Selected from 35 competing offers. Located in the coveted Plano–Frisco corridor surrounded by Fortune 500 HQs. Phased renovation to Marriott Gen 6 standards. Features TopGolf amenities, Starbucks Bistro, and 1,508 SF of meeting space on 3.77 acres.

Active · Operating

Home2 Suites by Hilton — Tampa

Tampa, FL · 106 Keys · 2017 Build · USF / Busch Gardens Corridor

$23.56MPurchase price
$27.2MClosing appraisal
$3.64MEquity gain at closing
1.96xThesis equity multiple

Institutional-quality extended-stay asset directly across from the University of South Florida. Demand driven by Moffitt Cancer Center, Shriners Hospital, Busch Gardens, and USF's 45,000+ student campus. Minimal PIP obligations preserve near-term cash flow.

Opening Spring 2027

Hotel Rain — Hilton Outset Collection

Gulf Shores, AL · 49 Keys · Hilton Outset Collection · Luxury Boutique Resort

Ground-UpHilton Outset brand
Couples NichePrivate plunge pools
Premium ADRSwim-up bar · spa · dining
CoastalHigh-barrier market

Ground-up luxury boutique concept tailored exclusively for couples. Every suite features private balcony hot tubs and individual plunge pools. Central elevated courtyard pool with swim-up bar, luxury cabanas, and curated on-site dining. Targets the underserved high-end "honeymoon-style" market in a supply-constrained coastal destination.

Section 07 · The Demand Radius

Irreplaceable location. Permanent demand.

Every major demand generator in the Anaheim Resort District sits inside a short radius of 1752 S. Clementine Street — and no comparable site is available to build.

Stylized map of the Anaheim Resort District showing the hotel and nearby demand drivers
Holiday Inn Express
0.0M2025 Anaheim visitors
$0.0B2025 visitor spending
0.00M2025 convention attendees
$0.0B+Committed resort expansion

Sources: Visit Anaheim (2025 tourism release); TEA Global Experience Index; City of Anaheim. Distances are approximate from 1752 S. Clementine St. and are provided for geographic reference only.

Section 08 · The Business Plan

Acquire, convert, reposition, stabilize, monetize.

A sequence the co-sponsors have run across their hospitality portfolios, applied to a hotel that captures 77% of its fair RevPAR share today.

  1. 01

    Acquire

    Close the leasehold at a $21.0M basis, $162,791 per key — below replacement cost in the Anaheim Resort District.

    $18.1M senior loan at 60% loan-to-cost, 8.0% fixed with two years interest-only. Both sponsor principals are co-borrowers.

    Target date
    Thesis October 2026
  2. 02

    PIP and conversion scope

    $5.418M full IHG property improvement plan — $42,000 per key across exterior and arrival, lobby, breakfast, all 129 guestrooms and five corridor floors.

    $1.548M of IHG key money ($12,000/key) supports the conversion and is distributed to investors pari passu. Two-phase scheduling keeps the hotel open.

  3. 03

    Operational repositioning under NewcrestImage

    Close the RevPAR-index gap: the hotel captures a 77 index today, with an occupancy index of 81 and a rate index of 95 — the shortfall is share, not price.

    IHG One Rewards (160M+ members) plus professional revenue management drive low-cost direct demand.

  4. 04

    Stabilization

    RevPAR path of $81 actual → $103 (Year 1, renovation) → $143 → $152 → $162 stabilized, underwritten to a 113 index against the post-renovation comp set.

    NOI ramps from $1.41M in the renovation year to $3.18M in Year 3, a 35% stabilized margin on $9.0M of revenue.

  5. 05

    Thesis disposition window

    Institutional sale underwritten at an 8.2% exit cap: $39.9M value at Year 3 against a $17.9M loan balance.

    Value is created by repositioning NOI from $1.4M to $3.2M, not by assuming cap-rate compression.

    Target date
    Year 3–4 (thesis)

Operating Pro Forma · Years 1–5

Projected operating performance, years one through five
MetricYr 1 (Reno)Yr 2Yr 3Yr 4Yr 5
Occupancy63.5%76.0%77.5%77.5%77.5%
ADR$161.61$188.55$196.51$202.41$208.48
RevPAR$102.65$143.32$152.34$156.91$161.61
Total revenue$6.11M$8.30M$9.01M$9.23M$9.45M
Net operating income$1.41M$2.73M$3.18M$3.25M$3.27M
NOI margin23.0%32.9%35.3%35.3%34.6%

Year 1 reflects renovation disruption during the PIP; Year 2 captures the first full re-flagged year. Source: sponsor investment model. Projections only, not guarantees.

Moneil Investment Group

Section 09 · Sponsorship

One aligned sponsor, one experienced operator.

The sponsor principal is a co-borrower on the senior loan and co-invests 20% of the equity alongside limited partners.

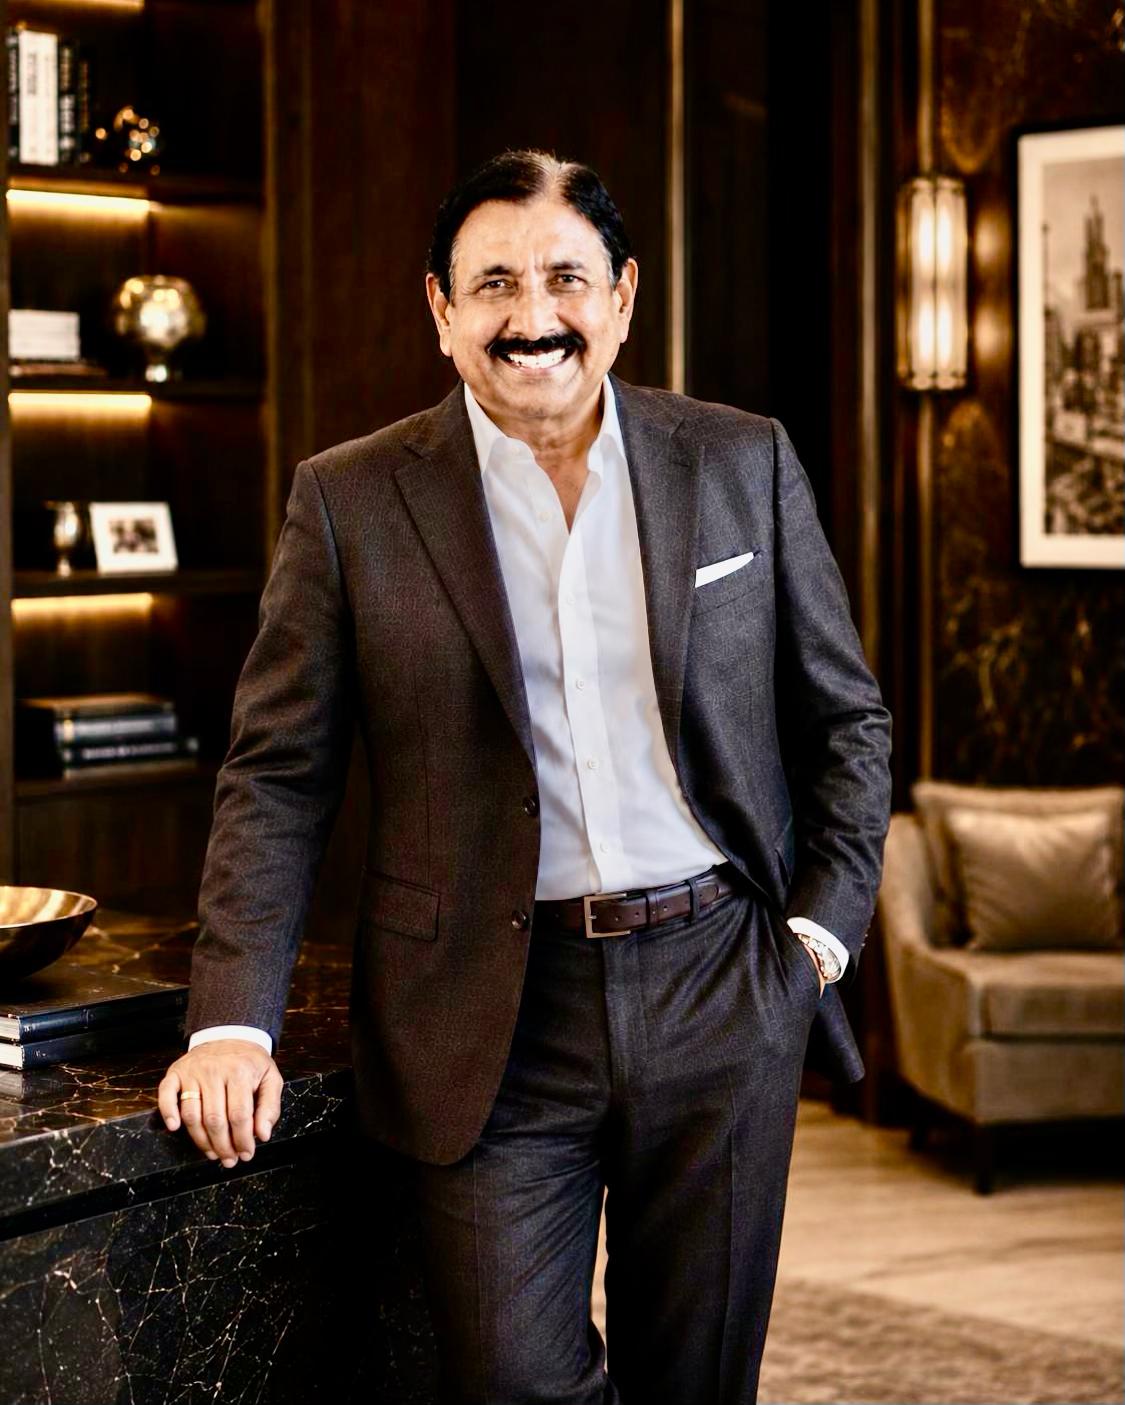
Portrait of Vinney (Smile) Chopra

Vinney (Smile) Chopra

Founder & CEO, Moneil Investment Group · Co-Sponsor and Co-Borrower

Vinney Chopra is the founder and CEO of Moneil Investment Group and a 5x Amazon bestselling author. He has raised $250M+ across 36 full-cycle deals spanning multifamily, senior assisted living, and hospitality, and is a co-sponsor and co-borrower on this transaction. He leads investor relations, capital formation, and asset-level oversight.

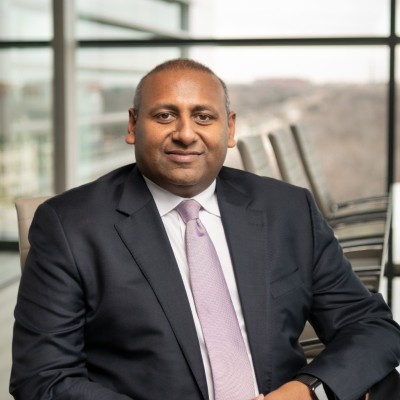
Portrait of Mehul Patel · NewcrestImage

Mehul Patel · NewcrestImage

Chairman & CEO, NewcrestImage Management LLC · Third-Party Hotel Operator

NewcrestImage Management LLC performs day-to-day hotel operations, bringing a track record of 300+ hotel deals and $3B+ transacted. The operator leads the conversion ramp, revenue management, and the IHG brand-standard transition following the property improvement plan.

Section 10 · Investor FAQ

Questions accredited investors ask first.

What are we buying?

A 129-key La Quinta Inn & Suites at 1752 S. Clementine Street in Anaheim. The leasehold is being acquired for $21.0 million, or $162,791 per key, and converted to a Holiday Inn Express & Suites under IHG. The total project capitalization is $30.178 million, including the purchase, full PIP, financing, reserves, and fees.

What are the tax advantages?

The $5.418 million PIP creates a large depreciable basis at closing. A cost-segregation study may reclassify components into 5-, 7-, and 15-year assets, with 100% first-year bonus depreciation under current law. Illustrative K-1 losses are estimated at 50–60% of invested capital in each of Years 1 and 2, or roughly 110–120% cumulatively. Actual allocations depend on the final study, placed-in-service date, and each investor’s tax position. Passive losses generally offset passive income unless you qualify for Real Estate Professional Status. This is not tax advice; consult your own CPA.

How close is the hotel to Disneyland and other demand drivers?

The Disneyland Resort gates are 0.5 miles away, Disney California Adventure is 0.9 miles away, GardenWalk is 0.1 miles away, and the Anaheim Convention Center is 0.4 miles away. The hotel is adjacent to Interstate 5 and 13 miles from John Wayne Airport. Anaheim welcomed 26.5 million visitors who spent $6.8 billion in 2025.

Is this a fee-simple purchase?

No. The investment acquires a leasehold interest, meaning the improvements are owned but not the land. The ground lease runs to 2096, leaving roughly 70 years against a thesis 3-to-4-year exit. Base rent is $541,000 annually and is already included in underwritten NOI. CPI resets occur every four years with a 10% floor and 25% cap per reset.

What does the renovation include, and will the hotel remain open?

The $5.418 million, two-phase IHG property improvement plan covers every guest-facing space: guestrooms and baths, lobby and great room, Express Start breakfast area, all five guest-floor corridors, Express Shop, exterior, porte cochere, and brand signage. The work is phased so the hotel can continue operating throughout construction.

What is IHG contributing, and why Holiday Inn Express?

IHG is contributing $1.548 million of key money, or $12,000 per key, received and distributed to investors pari passu in Year 2. Holiday Inn Express has 3,300+ hotels and 353,000 rooms in more than 50 countries, supported by 160 million+ IHG One Rewards members. IHG currently represents only 611 of roughly 21,000 Anaheim hotel rooms, a 2.91% share.

How is the hotel performing today, and what is the operating thesis?

Trailing twelve months performance was 55.1% occupancy, $147.64 ADR, and $81.38 RevPAR, equal to a 77 RevPAR index. The occupancy index is 81 while the rate index is 95, indicating that the shortfall is primarily share and brand rather than price. The thesis stabilizes at $162 RevPAR and a 113 index following renovation, reflagging, and professional revenue management.

What are the debt terms?

The capital stack includes an $18.107 million senior loan at 60% loan-to-cost, fixed at 8.0%, with two years of interest-only payments followed by 25-year amortization. A $1.449 million interest reserve supports the renovation ramp. There is no floating-rate exposure and no refinancing is required within the thesis exit window.

What are the investment classes and minimums?

Class A begins at $250,000 for investments from $250,000 to $499,999, with a 70/30 LP/GP operating split, a thesis 21.8% net IRR, and a 1.74x equity multiple. Class B begins at $500,000, with a 75/25 split, a thesis 23.2% net IRR, and a 1.80x multiple. Both classes include a 2% annual asset-management fee and 2% loan-guaranty fee. Definitive terms are governed by the offering documents.

How and when are distributions modeled?

The model shows operating cash flow during the hold and proceeds at sale. For an illustrative $250,000 Class A investment, modeled cash flow is $17,630 in Year 1, $35,469 in Year 2, and $18,797 in Year 3, plus a $113,268 equity gain at sale. Year 2 includes the $1.548 million of IHG key money. These are projections, not guarantees; actual timing is governed by the PPM and operating results.

What is the exit strategy?

The thesis is an institutional sale in Year 3 or Year 4 at an 8.2% cap rate, without assuming cap-rate compression. The modeled value creation comes from increasing NOI from approximately $1.4 million to $3.2 million. The Q&A models $20.29 million of net equity at a Year 3 exit and $23.0 million at a Year 5 exit after loan payoff and 1.5% exit costs.

What are the principal risks?

Principal risks include the leasehold and ground-rent structure, renovation timing and cost overruns, demand volatility, brand-ramp execution, new supply, financing and exit-cap conditions, illiquidity, and the possible loss of some or all invested capital. The two-phase PIP, fixed-rate debt, interest reserve, working capital, and diversified leisure and convention demand are underwriting mitigants, not guarantees. Review the complete risk factors in the PPM.

Who can invest, and how do I receive the offering documents?

This Regulation D Rule 506(c) offering is available only to verifiable accredited investors. Schedule a call with Vinney first to discuss the opportunity and fit. A qualified third party must then verify accredited status before the Private Placement Memorandum, Operating Agreement, and Subscription Agreement are released and a subscription can be completed.

Section 10 · How to Invest

Three steps from interest to funded.

  1. 01

    Schedule a call with Vinney

    Choose a time on his calendar. On the call you can ask questions about the asset, the conversion, and the capital stack, and learn what materials are available to accredited investors.

  2. 02

    Review the PPM and speak with the sponsor

    Once your accredited status is verified, the Private Placement Memorandum, Operating Agreement, and Subscription Agreement are released. Bring your questions to a direct call with Vinney.

  3. 03

    Complete subscription documents and fund

    Execute the subscription, choose Class A or Class B, and wire committed capital ahead of the thesis October 2026 closing. Raise-close, funding, and first-distribution dates are confirmed in the PPM.

Start with a conversation

Before anything else, schedule a phone call or Zoom meeting with Vinney. On that conversation he will walk you through the asset, the capital stack, and the offering documents, and help you determine whether you meet the eligibility criteria — including accredited investor status under Reg D Rule 506(c) — before any materials are released.

Portrait of Vinney Chopra, Founder and CEO of Moneil Investment Group

A personal note

I have spent my career raising money from people who worked hard for it — physicians, business owners, families building something for their children. I do not take that lightly. Every deal we sponsor, my partners and I put our own capital in beside yours and sign on the loan, because I believe a sponsor should feel exactly what an investor feels. On this hotel we bought measurable underperformance in a location that cannot be replicated, and our job now is simple stewardship: execute the conversion, run it well, and return your capital with the profit we underwrote.

God bless you. Smile and Succeed.

Vinney Chopra · Founder & CEO, Moneil Investment Group

Schedule a one-on-one call with Vinney to discuss the Anaheim Resort District hotel.

Available to verified accredited investors only · Reg D Rule 506(c)